
A trend deck lands on your desk with ten things on it and you have budget for two. What it does not tell you is which of them is an enforceable requirement, which is a genuine shift with adoption behind it, and which is a guess that has been repeated often enough to sound settled.
Here are the eight that currently matter, and what each one actually changes about a carton.
1. Regulation Is Driving More Change Than Consumer Preference
The strongest force acting on retail packaging in 2026 is a compliance deadline, and it is already pricing design decisions whether or not you are tracking it.
In the United States, seven states have enacted packaging extended producer responsibility laws: Maine, Oregon, Colorado, California, Minnesota, Maryland and Washington. As of September 2026, only Oregon and Colorado are actually collecting fees. Oregon began in July 2025 and its law was upheld in federal court in August 2026; Colorado began in January 2026.
One figure needs correcting because it circulates constantly. You will read that 34 states have EPR laws. That count is accurate and is not about packaging: it covers every product category carrying an EPR program somewhere in the US, paint and mattresses and batteries included. For packaging specifically it is seven enacted, two billing.
The mechanism that reaches your carton is eco-modulation. Fees start from weight and material category, then adjust for design: lower for mono-material construction, recycled content, right-sizing and curbside recyclability, higher for constructions that are harder to recycle. For a fiber pack, the components that push a fee upward are the non-fiber ones, meaning laminate films, foil and plastic windows. No program publishes a per-attribute figure for paperboard, so the direction is knowable while the exact magnitude is not.
In the EU, the packaging regulation began phased application in August 2026. Three points are routinely misreported:
- The recycled content mandate is plastic-only. It does not apply to paper or fiber packaging at all.
- Recyclability grades A, B and C exist, but the criteria defining them do not yet. The delegated acts are not due until 2028, so “what grade is my pack” is currently unanswerable.
- A paper pack carrying five percent or more plastic is treated as single-use plastic, with consequences for certain applications from 2030. That is the sharp edge for laminated and foiled cartons.
A fourth provision catches more packs than brands expect: packaging with features aimed only at inflating perceived product volume, including double walls and false bottoms, may not be placed on the market. And the Declaration of Conformity is signed by the brand placing the product on the EU market, not by the converter.
What it changes for you: compliance now depends on specification data most brands do not hold. Substrate, caliper, blank weight, coating coverage, window and foil materials, ink and adhesive. The trend is really a data requirement landing on your bill of materials. Our guide to EPR packaging compliance covers which states apply and what your converter owes you.
2. The Move From Barcodes to 2D Codes
Retail is transitioning from one-dimensional UPC barcodes to two-dimensional codes such as QR, which carry far more data: product variants, production and expiry dates, and links to fuller product information, alongside the standard identifier.
Retailers are upgrading point-of-sale scanners to read them. Brands are adding 2D codes carrying their GTIN under GS1 Digital Link standards. The industry target year is 2027.
The nuance most coverage misses: GS1 US does not publish an exact date within 2027, and states that implementing every 2D capability by then is not necessary. It is a transition target rather than a hard deadline. The recommended approach during the changeover is dual barcoding, carrying both codes on pack.
What it changes for you: a second code is artwork real estate, a quiet-zone requirement and a print-quality requirement. All three are decided at prepress, on the dieline, not at artwork approval. Retrofitting one is a panel redesign. Our guides to QR codes on packaging and connected packaging cover the print constraints and the uses that justify them.
3. Paperization, and Where It Stops
Paperization means substituting paper-based structures for plastic ones, and the industry language has shifted from pilots to scale. Paper now achieves cost parity or preference against plastic in over half of total-cost-of-ownership evaluations, and barrier grades exist that run on standard form-fill-seal machinery without converter modifications.
Where it stops is as useful as where it works. Peer-reviewed work on bio-based barrier coatings identifies moisture, temperature and gas tolerance, alongside cost, as the persistent obstacles. Packaging bodies have also cautioned against substituting materials without life-cycle analysis, and against assuming a fiber structure holds product integrity and food safety as well as the polymer it replaced.
What it changes for you: probably less than the coverage suggests. Paperization is a flexibles story, about replacing multi-layer plastic laminates. If you are already in a folding carton, you are not paperizing. The useful insight runs the other way: the barrier problem paperization is trying to solve is exactly why, in most packs, the carton does not carry the barrier. That job sits with the primary container.
4. Mono-Material Simplification
Fewer glued joints, fewer components, easier separation at end of life. The design goal is packaging that is operationally simpler while still performing on shelf.
This one is worth taking seriously for a reason beyond aesthetics: it is directly rewarded by EPR eco-modulation. Mono-material construction is one of the characteristics that adjusts a fee downward, so the logic connects to the regulation above and is checkable rather than asserted.
What it changes for you: every non-fiber element on a fiber pack is now a cost as well as a design decision. A window, a foil, a laminate. Worth pricing each against what it earns.
5. Refillable and Reusable Formats
Refill gets more coverage than its share of sales currently justifies, and the numbers are more useful than either the enthusiasm or the backlash.
In US prestige fragrance, where the data is clearest, refillable bottles and refills account for around 5 percent of sales, having grown 69 percent over two years, while one in five consumers say they prefer brands offering a refill option. Refills typically price around 30 percent below a new bottle.
The interesting number is the gap. One in five state a preference; five percent actually buy. That is a measurable difference between what consumers say and what they do, inside a single dataset, and it is a better planning input than the claim that refill is going mainstream.
What it changes for you: refill is a credible positioning play with real, compounding growth from a small base, and adoption has been slower than the narrative implies. Design for it where it fits the brand. Do not build a volume forecast on it.
6. Certified Fiber, and What the Label Actually Certifies
Chain-of-custody certification is now close to standard on premium fiber packs, which makes it worth knowing what it does and does not tell you.
FSC chain of custody certifies the tracking system, not the pack. It verifies that certified material is used, tracked through manufacturing, and recorded through purchase and sale. It says nothing about the quality of the carton.
The label tiers differ meaningfully. FSC 100% is entirely virgin fiber from certified forests. FSC Mix combines certified virgin and recycled fiber with controlled wood. FSC Recycled is fully recycled fiber that has been verified, which is the distinction from an unverified generic recycled claim. SFI’s chain-of-custody standard is PEFC-endorsed so those two interoperate; FSC stands separately.
What it changes for you: certificates are publicly searchable. Ask a supplier for the code and check it rather than accepting a logo, and ask which label tier they hold. Our guide to sustainable packaging certifications sets out what each scheme covers.
7. Tactile Finishes and Lighter Luxury
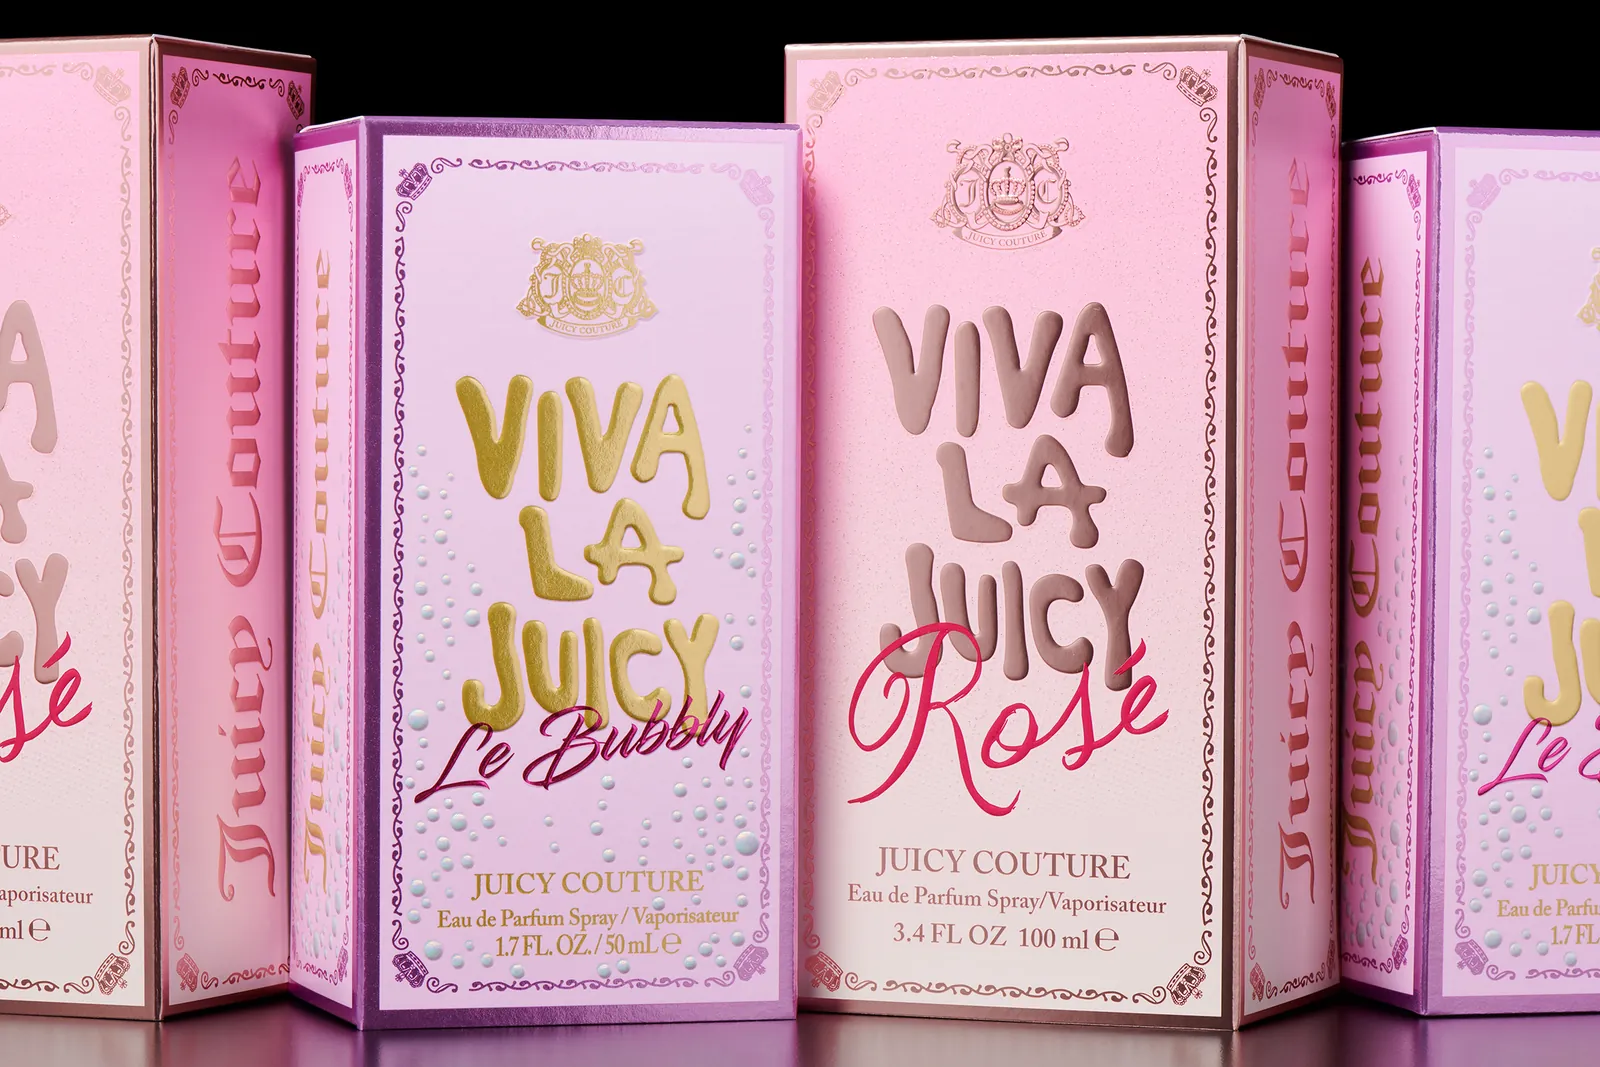
The clearest design shift is toward texture rather than mass. Premium positioning is increasingly signaled through a textured surface or a distinctive silhouette rather than through weight and heavy materials, partly because packaging is now seen on a screen before it is held, and a flat photograph cannot convey heft.
That moves value toward decorated paperboard and away from heavy glass and rigid board, which is a genuine opportunity for anyone already buying cartons.
Where the evidence stops: several trends that appear on most 2026 lists could not be traced to any credible source. Soft neutral palettes, heritage revival and gender-neutral design all appear repeatedly in supplier blogs citing one another, with nothing underneath. You will also find confident claims that minimalism dominates 2026 and, in the same search results, that 2026 is a rebellion against minimalism. Both are asserted without research. Treat the design conversation as the least reliable part of any trend deck.
What it changes for you: the finishing decisions that carry perceived value, emboss, foil, specialty coating, are the ones worth budget. There is real research showing identical products in premium versus economy packaging rated 45 percent higher in expected value, with buyers willing to pay 30 percent more, against a production cost difference of under 9 percent. Our guide to packaging psychology covers the perception mechanisms in more depth.
8. One Pack, Two Channels
A pack now has to work as a physical object on a shelf and as a small thumbnail on a screen. E-commerce accounted for 16.9 percent of US retail sales in the first quarter of 2026, and for most consumer brands the first encounter with a pack is an image rather than the object.
The two jobs pull in different directions. Shelf presence rewards detail, finish and structure that read at arm’s length. A thumbnail rewards bold shapes, high contrast and a brand mark legible at a couple of hundred pixels. Finishes that carry a shelf, such as a subtle emboss or a matte texture, do not photograph.
What it changes for you: design for both deliberately rather than hoping one carries the other, and check artwork at thumbnail size before signing it off. Products sold through both retail and e-commerce frequently need two specifications rather than one compromise.
What to Do About These
Five practical consequences, in the order they hit a project.
1. Treat specification data as a compliance asset
Substrate, caliper, blank weight, coating type and coverage, window and foil materials, ink and adhesive. This is what every current regulation asks for and most brands cannot answer. Ask your converter for a written composition sheet per pack, keep it with the artwork, and build the record once so it can be reused each reporting year.
2. Decide the 2D barcode question at dieline stage
Not at artwork approval. A second code is panel space plus a quiet zone plus a print-quality requirement, and retrofitting it is a redesign.
3. Price finish decisions against eco-modulation, not just unit cost
A film laminate, a foil and a plastic window each move a fee in the same direction. The magnitude is unpublished; the direction is not. The lowest-priced finish on a quote is not always the lowest-cost finish across a reporting year.
4. Ask what a sustainability claim actually certifies
Chain of custody certifies tracking. A management system standard certifies a system. A carbon-neutral claim needs a stated boundary, because a carbon-neutral site is a much narrower claim than a carbon-neutral company.
5. Check artwork at thumbnail size before approval
If the brand mark and the variant are not legible at a couple of hundred pixels, the pack will underperform online regardless of how it looks on a shelf.
How Arkay Reads These Shifts
A converter sees trends differently from a forecaster, because they arrive as production requests rather than predictions. What we see on the floor is mostly the first item above: brands asking for composition data they have never needed before, and asking earlier in the process than they used to. That is as true in food and nutraceuticals, where regulatory pressure lands hardest, as it is in beauty.
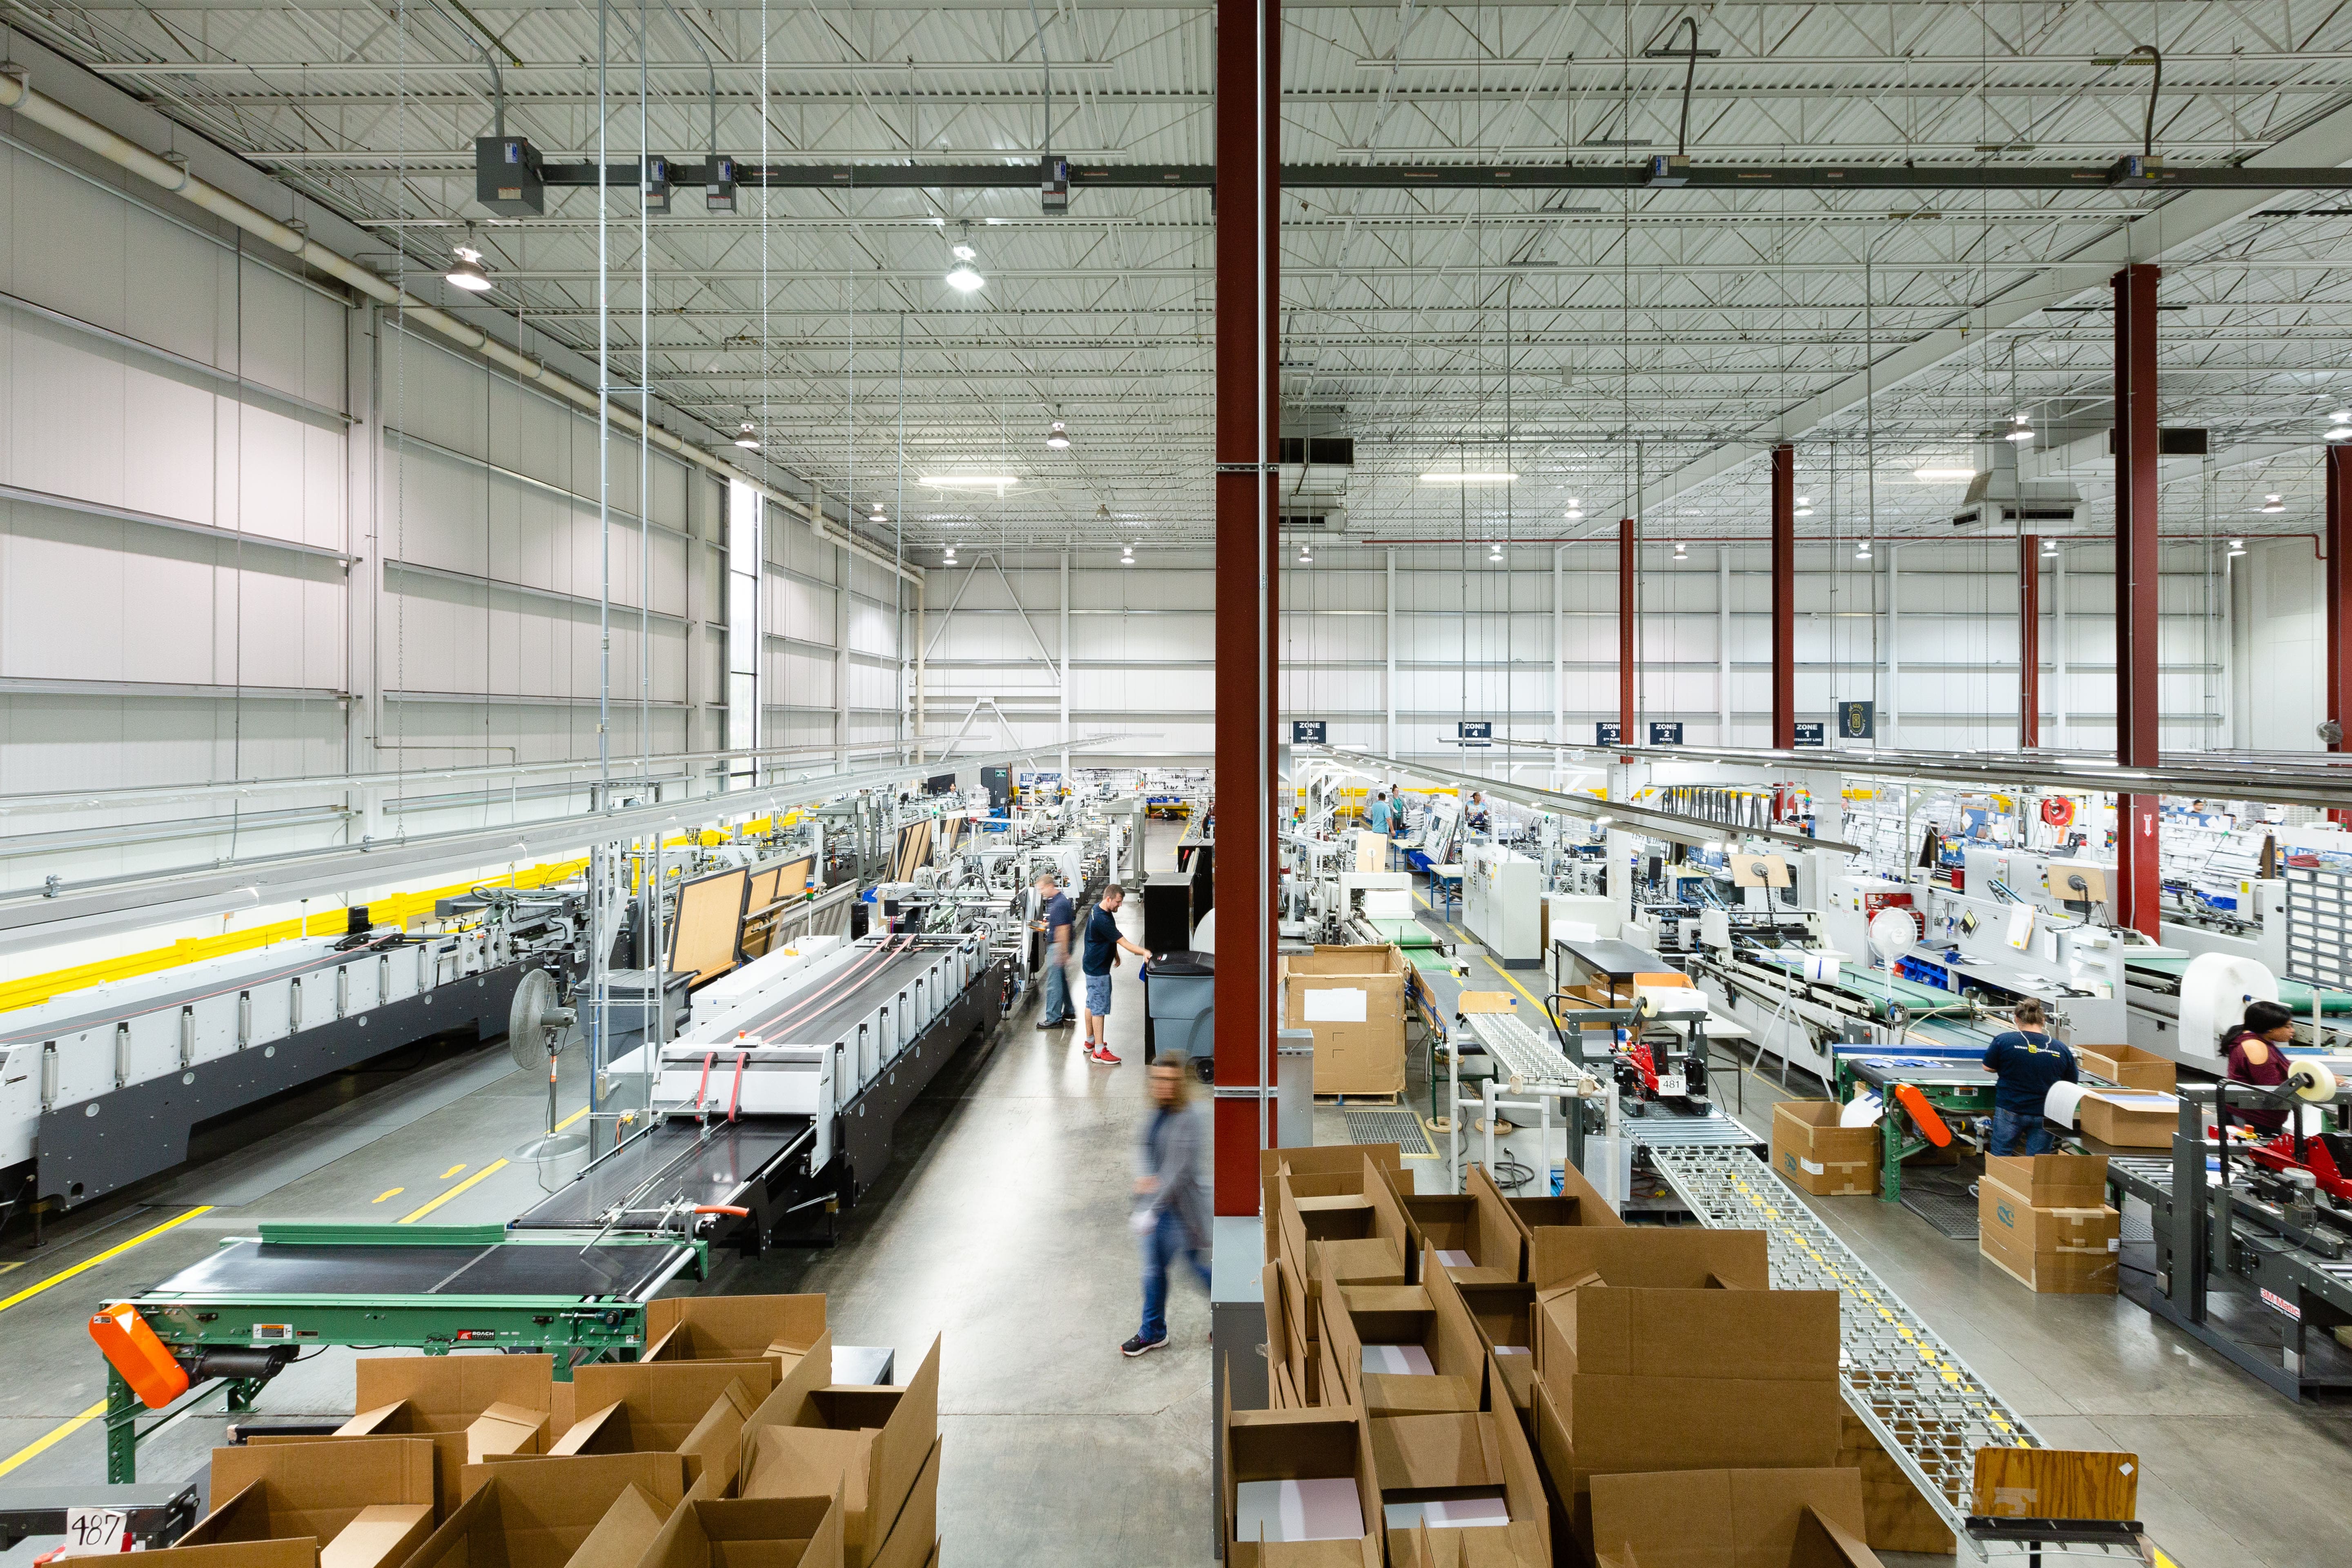
After four generations and a century of folding carton production since 1922, our position on most of this is narrow by design. We print offset on solid bleached sulfate board only, in a 14 to 28pt caliper range, from a carbon-neutral 140,000 square foot plant in Roanoke, Virginia. That consistency is what makes a reported substrate figure hold across a year of production rather than varying by delivery.
On the finish decisions regulation now prices: we run inline soft-touch aqueous coating rather than soft-touch film lamination, which matters because a coating adds no separate plastic layer to the board. We coat with flexo rather than printing with it, running two double flexo coaters for inline pearlescent, gold and silver effects. Emboss and deboss hold to ±0.3mm registration.
Fiber sourcing is triple-certified to FSC, SFI and PEFC, and the plant holds BRCGS packaging safety certification and an EcoVadis Platinum rating held consecutively since 2022. Per-project sustainability spec sheets covering substrate certification, finish composition and recyclability characteristics are available on request, which is increasingly what the compliance conversation actually needs. Our sustainability credentials set out what each covers.
Tell Us Which of These Affects Your Next Run
Let’s talk about the two or three that touch your program, rather than all eight.
For most brands the list is shorter than a trend deck suggests: whether a 2D code needs panel space, whether a finish decision is quietly raising an EPR fee, and whether you can answer a composition question about a pack you already buy. All three are inexpensive to settle before a dieline is cut.
Send us a carton spec and the markets you sell into, and we will tell you which of these is real for you and which is noise.
Reach out to Arkay’s team with a spec, or with a trend claim you want checked.
Two guides go deeper: packaging innovation trends on the technology side, and what makes packaging recyclable on recyclability as a design property rather than a label.
Frequently Asked Questions
Which packaging trend should a brand act on first?
Regulation, more than anything consumers are doing. Extended producer responsibility is enacted in seven US states with two currently billing, and the EU packaging rules began phased application in August 2026. Both carry published dates and both price design decisions directly, through fee structures that charge more for non-fiber components on a fiber pack. That makes them the trends you can plan against rather than speculate about. It also makes specification data the practical priority, since compliance depends on knowing your substrate, caliper, coating coverage and window and foil materials, which is exactly what most brands cannot produce on request.
What packaging data should I be able to get from my carton supplier?
Enough to classify and weigh every component: substrate type and grade, caliper, blank weight, coating type and coverage, the presence and material of any window or foil, the ink system and the adhesive type. This is the data every current packaging regulation asks for, and a single pack weight will not do, because programs charge by material category and a carton with a plastic window spans two of them. Ask for it as a written composition sheet rather than a verbal assurance, keep it with the artwork, and build the record once so it can be reused each reporting year rather than reconstructed under deadline.
Does the EU recycled content mandate apply to paperboard?
No. The recycled content targets in the EU packaging regulation apply to plastic packaging only, stepping up by category in 2030 and again in 2040. They do not apply to paper or fiber-based packaging at all. This is one of the most commonly misstated points in packaging content and is worth checking against any supplier claim. What does apply to a fiber pack is the recyclability grading framework, where the honest position is that the grades exist while the criteria defining them do not, since the delegated acts setting them are not due until 2028.
Is unprinted brown board a sustainability signal or a cost decision?
Usually a cost decision that gets described as a sustainability one, and the industry guidance is less forgiving about it than brands expect. ECR Europe’s shelf-ready packaging standard states directly that unprinted brown corrugate can reduce the quality of the shopper experience and should be avoided. Unprinted board is not inherently more recyclable than printed board either, since recyclability is driven by the substrate and by any non-fiber components rather than by ink coverage. If the goal is genuinely lower impact, the levers that move it are material reduction, mono-material construction and avoiding laminates.
Does packaging EPR apply in my state yet?
Probably not yet, depending on where you sell. Seven US states have enacted packaging extended producer responsibility laws, and as of September 2026 only Oregon and Colorado are actually collecting fees. A figure of roughly 150 EPR laws across 34 states circulates widely and is accurate but not about packaging: it covers every product category carrying an EPR program somewhere, including paint, mattresses and batteries. For packaging specifically the number is seven enacted and two billing, which is a much narrower exposure than the headline suggests.
What does eco-modulation change about what a carton costs?
It turns design decisions into line items. Extended producer responsibility fees start from weight and material category, then adjust for design characteristics: lower for mono-material construction, recycled content, right-sizing and curbside recyclability, and higher for constructions that are harder to recycle. For a fiber pack, the components that push a fee upward are the non-fiber ones, meaning laminate films, foil and plastic windows. The mechanism is clear and documented. What is not available is a published per-attribute figure for paperboard, so the direction is knowable while the exact magnitude is not.